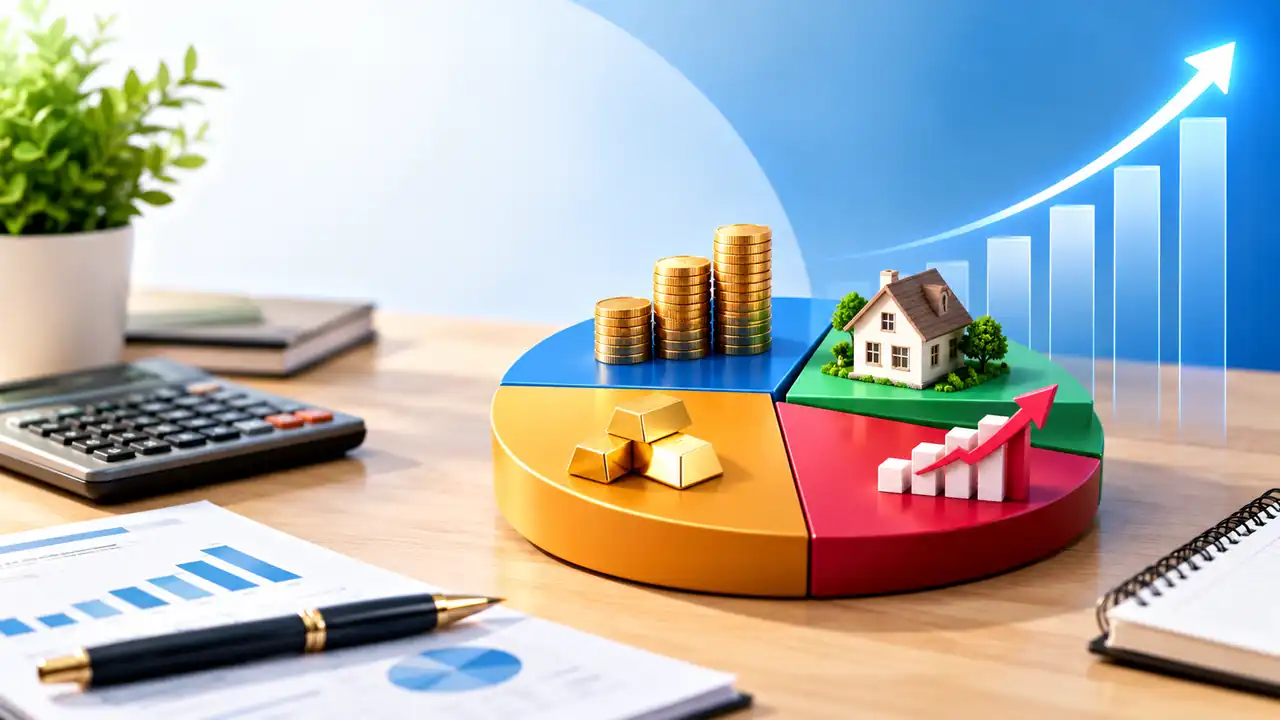
The selection of mutual fund investments is generally linked to picking the appropriate scheme, studying previous gains or losses, or opting for schemes that have good growth prospects. But successful mutual fund investing not only involves picking out individual schemes but also asset allocation, which is just as critical as the schemes themselves because it helps decide where you allocate your investments among various types of assets like equity, debt, gold, and other securities.
It may help you manage risks, minimize volatility effects, and stay focused on your objectives.
What Is Asset Allocation?
Asset allocation refers to dividing your investments among different asset classes based on your financial goals, risk tolerance, investment horizon, and market conditions.
For example, an investor may allocate their portfolio as follows:
- 60% to equity mutual funds
- 25% to debt mutual funds
- 10% to gold
- 5% to other assets
The appropriate allocation will differ from one investor to another. Someone investing for a long-term retirement goal may be comfortable with a higher equity allocation, while an investor approaching a short-term financial goal may prefer more debt exposure.
The main idea is simple: do not depend on a single asset class to achieve all your financial goals.
Why Asset Allocation Matters in a Mutual Fund Portfolio
It Helps Manage Portfolio Risk
Various asset classes will respond differently to market and economic events. While equities can show great growth potential in the long term, they might have short-term volatility. Meanwhile, debt securities tend to be more stable, and gold sometimes behaves differently from both equities and debt.
Diversifying assets in a portfolio makes an investor less dependent on the performance of any particular type of investment.
For example, if there is a sharp correction in the equity market, the portfolio containing debt and gold might suffer less than a portfolio that includes only equities.
But diversification does not decrease investment risks; it just distributes them.
It Creates a Better Balance Between Growth and Stability
Equity mutual funds are generally used to generate long-term capital appreciation, while debt-oriented funds can provide relatively greater stability and help meet shorter-term requirements.
Consider an investor with a 70:30 equity-to-debt allocation. During a strong equity market, the equity component can drive portfolio growth. During periods of market volatility, the debt component can provide some stability.
The right balance depends on the investor rather than a fixed formula. A young investor with a long investment horizon may be able to tolerate more equity exposure, while someone nearing retirement may need a more conservative allocation.
It Aligns Investments with Financial Goals
Asset allocation should be connected to why you are investing.
A long-term goal such as retirement may allow for a higher allocation to equity because the investor has more time to withstand market fluctuations. On the other hand, money required for a goal within the next few years may need greater exposure to relatively stable assets.
For example, an investor saving for a child’s education in 12 years may initially maintain a higher equity allocation. As the goal approaches, gradually increasing the allocation towards debt can help reduce the impact of a sudden equity market correction.
This approach is sometimes referred to as a glide path, where portfolio risk is gradually reduced as the financial goal gets closer.
How to Build an Asset Allocation Strategy
The first step is to identify your investment goals and time horizon. Determine how much money you need, when you need it, and how much volatility you can realistically tolerate.
Next, decide your broad asset allocation. Instead of selecting mutual funds first, determine how much of your portfolio should be allocated to equity, debt, gold, and other suitable assets.
After that, choose mutual funds that fit each allocation.
For example, an equity allocation could include diversified categories such as large-cap, flexi-cap, or multi-cap funds rather than concentrating the entire equity portfolio in a single sector. Similarly, the debt portion can be selected based on the investor’s time horizon and risk requirements.
Rebalancing Keeps the Portfolio on Track
Asset allocation is not a one-time decision. Market movements can cause your portfolio’s allocation to drift significantly.
Suppose you initially invest 60% in equity and 40% in debt. If equity markets rise sharply, your portfolio might eventually become 70% equity and 30% debt. While the portfolio may have generated good returns, it is now taking more equity risk than originally intended.
Rebalancing involves bringing the portfolio back towards its target allocation.
This can be done periodically or when an asset class moves significantly away from its target percentage. Rebalancing can also encourage disciplined investing because it may involve reducing exposure to an asset class that has risen substantially and adding to one that has underperformed.
Avoid Over-Diversification
However, diversification through asset allocation does not imply having more and more mutual funds. It is possible to hold many funds investing in the same stocks or industry, which will give a false impression of having a diverse portfolio when in fact concentration is still high.
As an illustration, having five equity funds does not automatically lead to a diversified portfolio if all of them have major investments in the same companies or industries.
The Bottom Line
Allocation of assets helps diversify mutual fund portfolios to strike a balance between growth and risk management. Investors need not try to identify the asset classes that will produce high returns every year, but rather create a portfolio that is able to sustain them in various market conditions.
The optimal allocation varies based on the investor’s objectives, investment period, risk profile, income, current investment status, and other issues. It needs to be revised now and then, since an investor’s situation and goals may change.
It must be noted that successful mutual fund investing is not just about identifying top-performing mutual funds, but rather creating an appropriate portfolio composition and following through with discipline.