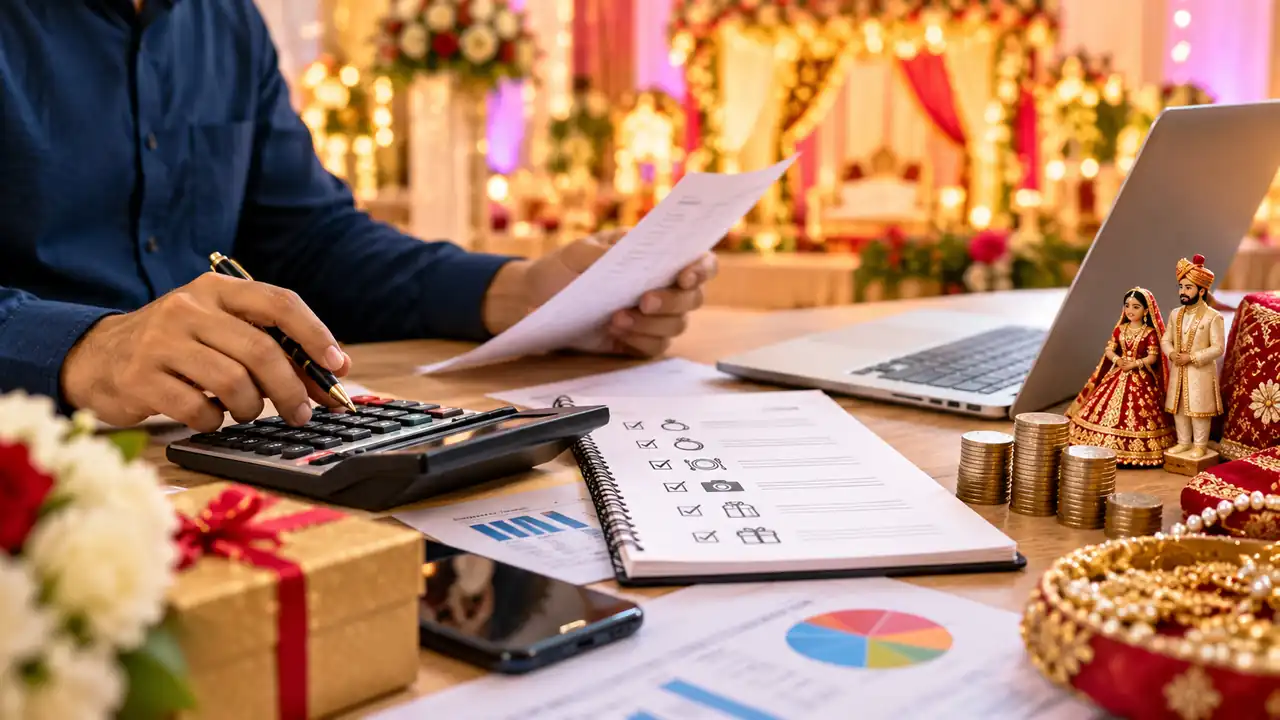
Wedding expenses can add up quickly, from venue and catering to clothes, photography and travel. A marriage loan can help cover a funding gap, but the amount you borrow should be based on what you actually need and can repay, not the maximum amount a lender offers.
First, classify your wedding expenses into two categories: costs that are mandatory and those which are optional or can be reduced or avoided. List each expected expense and add a realistic amount rather than rounding everything up. This can give you a base to plan how much your marriage loan should be before comparing lenders or trusted loan apps.
Build a Wedding Budget Before Applying
Make a simple list of expected costs and assign an amount to each:
- Venue and catering
- Décor and photography
- Clothing and jewellery
- Invitations and entertainment
- Travel and accommodation
- Other family or ceremony expenses
Then add the amounts. For example, if your estimated wedding cost is ₹25 lakh and you already have ₹10 lakh available through savings and family contributions, your initial funding gap is ₹15 lakh. You do not need to borrow the entire amount simply because that amount is available as a loan.
Keep a Buffer Without Inflating the Loan
Sometimes you may incur some additional wedding expenses when booking services. You can keep some contingency amount to cover any last-minute costs. Instead of taking a huge sum as contingency, calculate your budget first and then keep a modest buffer.
For example, if you have calculated your wedding expenses to be ₹20 lakh, you may keep an additional 1-2 lakhs as a contingency amount depending on your financial budget. It is important to include a buffer you can afford to repay, rather than using it as a reason to take a much larger loan.
Check Your Monthly EMI Before Finalising the Amount
The loan amount is only one part of the cost. Your monthly EMI should fit comfortably alongside rent, household expenses, existing EMIs, savings and other regular commitments. Suppose you borrow ₹5 lakh and the resulting EMI is ₹16,000 a month.
Hence, before applying, check whether you are able to afford the EMI even after wedding expenses are over. A practical approach could be to calculate your current monthly financial obligations first and figure out how much of a gap exists for a new EMI. Do not go ahead and take the loan amount only based on the maximum eligibility shown by a lender.
Account for the Total Cost of the Loan
Do not compare loans only by the amount you receive. Look at the total cost, including interest and applicable fees. For online loans, RBI requires regulated entities to provide a Key Fact Statement containing important loan details, including the Annual Percentage Rate. Fees and charges not disclosed in the KFS cannot be charged by the regulated entity during the loan term. This makes the KFS useful when comparing the actual cost of different offers.
Borrow for a Clear Funding Gap
Once you know your wedding budget, available savings and affordable EMI, you can arrive at a more realistic borrowing amount. Here is a realistic example:
| Expense | Amount |
| Estimated wedding cost | ₹25 lakh |
| Savings/family contribution | ₹10 lakh |
| Funding gap | ₹15 lakh |
| Contingency | ₹1 lakh |
| Planned borrowing need | ₹5.4 lakh |
This does not mean you must borrow exactly ₹16 lakh. Check whether the additional ₹1 lakh is genuinely needed and whether the resulting EMI fits your budget.
Compare Loan Options Carefully
Many trusted loan apps can make it easier to check available loan options and complete applications online. However, convenience should not replace checking the lender behind the offer, the loan terms and the total cost.
RBI advises borrowers to verify that a digital lending app is associated with an RBI-regulated bank or NBFC. Its digital lending framework also requires important loan information to be disclosed to borrowers.
Before accepting an offer through a loan app, check:
- Lender name and regulated entity details
- APR and applicable charges
- Loan tenure and EMI
- Repayment schedule
- Grievance redressal details
Recheck the Budget Before You Borrow
Wedding planning often changes between the first estimate and the final bookings. Revisit your figures after major expenses are confirmed. If your savings increase or a family contribution covers an expense, reduce the amount you plan to borrow.
A marriage loan should fill a specific funding gap, not become a way to expand the wedding budget. Taking only what you need can keep the repayment burden more manageable after the celebrations are over.